Home › Budgeting › Semi-Monthly Paycheck Budget
How to Budget When You Get Paid on the 15th and 30th: The Semi-Monthly Plan That Works
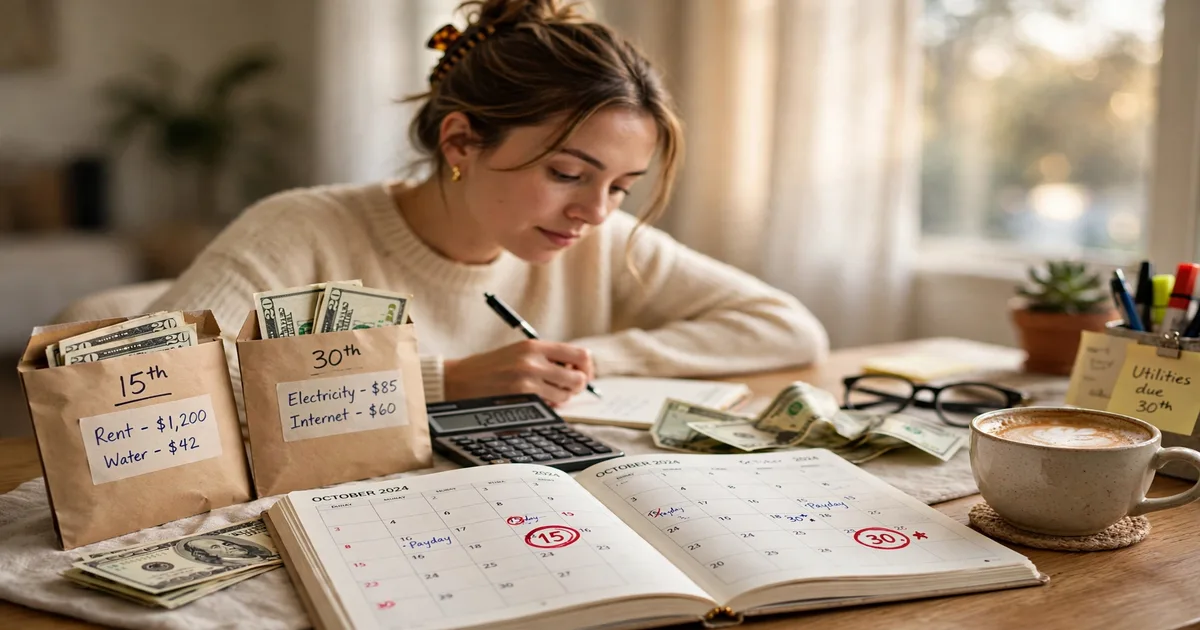
Getting paid on the 15th and 30th sounds simple — two paychecks, one month, done. But if you're learning how to budget when you get paid on the 15th and 30th, you've probably noticed the trap: rent is due on the 1st, your biggest paycheck lands on the 30th, and somewhere around the 22nd your account is somehow running on fumes. It's not a discipline problem. It's a timing problem. This guide gives you the exact semi-monthly budget system that fixes it: split your bills between your two paychecks by due date, use the half-payment method for the big ones, and pay yourself first — with a full worked dollar example you can copy.
What a Semi-Monthly Budget Really Means
Most budgeting advice assumes a monthly rhythm: one paycheck (or one mental bucket), one set of bills, one savings transfer. But when you're paid twice a month, your money arrives in two waves — and a single monthly budget hides the gap between them.
A semi-monthly budget is simply a plan that matches the rhythm your pay actually arrives in. Instead of one monthly list, you make two mini-budgets: one for the 15th paycheck (covering everything due before the 30th) and one for the 30th paycheck (covering everything due before the 15th). Same bills, same month — just planned in the order the money shows up.
Why does this matter so much? Because the #1 reason semi-monthly budgets fail is what planners call the "rent problem": a huge bill due on the 1st being paid from a paycheck that landed just 24 hours earlier, leaving the whole first half of the month fragile. Fix the timing, and the budget almost runs itself. (If you're paid every two weeks instead of twice a month, our biweekly budget guide is the one to follow — the calendar math is different.)
Step 1: List Every Bill by Its Due Date
The first move in paycheck budgeting is brutally simple: grab a sheet of paper (or open our free budget planner) and list every recurring bill with its exact due date. Not the month — the date. Rent, car payment, insurance, phone, internet, utilities, streaming, credit card minimums, loan payments. All of them.
Then split the list into two halves:
- Due the 16th through the 31st → these come from your 15th paycheck.
- Due the 1st through the 15th → these come from your 30th paycheck.
That second line is the one that surprises people. The paycheck you get on the 30th doesn't fund "the rest of the month" — it funds the first half of next month. Your 30th paycheck is really your "1st paycheck." Once you see it that way, the mystery of the 22nd-of-the-month emptiness disappears: you were spending the 15th paycheck's money on bills the 30th paycheck should have covered.
Variable costs (groceries, gas, eating out) get split roughly in half too — half from each paycheck — since you spend them evenly through the month.
Step 2: Give Each Paycheck Its Own Bill List
Now budget by paycheck: write out exactly what each paycheck must cover before the next one lands. This is the core of the whole system. A single monthly budget says "groceries: $500." A paycheck budget says "15th paycheck: groceries $250, phone $75, internet $70, savings $200." It names the money's job while the money is still in your account.
Two practical rules make this work:
- Round bills up, income down. Budget the electric bill at $150 even if it's usually $132. Budget the paycheck at what actually hits your account, not the gross. The small cushion this creates is your margin for error.
- Schedule savings like a bill. Before you split what's left, move your savings target out — ideally to a separate account — on payday morning. If you wait until the 28th to save "whatever's left," the answer is always the same: nothing. Our pay-yourself-first guide walks through this habit in detail.
One more power move: call providers and ask to shift due dates. Most credit card companies, utilities, and even some lenders will move your due date at no cost — just ask for a few days after each payday. Two or three phone calls can untangle a whole lopsided month.
Step 3: Use the Half-Payment Method for Big Bills
Here's where the half payment method earns its reputation. Big bills — rent, a car payment, sometimes insurance — are often more than half of one paycheck. Paid whole from a single check, they gut that paycheck and make the entire half-month fragile.
The fix: split the bill across both paychecks. If rent is $1,600 due on the 1st, set aside $800 from the 15th paycheck and $800 from the 30th paycheck into a separate "rent" envelope or sub-account. By the 1st, the full amount is sitting there waiting — and neither paycheck ever felt the whole blow.
People use this for:
- Rent — the classic half-payment bill
- Car payments — a $385 payment becomes two painless $192.50 halves
- Insurance premiums — car insurance, renter's insurance
- Savings goals — $400 a month becomes $200 per paycheck, automatically
The Consumer Financial Protection Bureau has free worksheets for mapping bills to paydays, but honestly, the half-payment method plus a two-envelope (or two-sub-account) setup covers 90% of what people need. Simple beats fancy every time.
Worked Example: How to Budget When You Get Paid on the 15th and 30th ($4,200/Month)
Theory is nice; let's run the actual numbers. Meet the example: take-home pay of $4,200 a month, split into two paychecks of $2,100 each — one on the 15th, one on the 30th.
Monthly bills and targets:
- Rent: $1,600 (due 1st)
- Car payment: $385 (due 5th)
- Car insurance: $175 (due 8th)
- Electric: ~$140 (due 12th)
- Phone: $75 (due 18th)
- Internet: $70 (due 22nd)
- Credit card minimum: $90 (due 25th)
- Subscriptions: $45 (scattered)
- Groceries: $500/month
- Gas/transport: $220/month
- Savings target: $400/month
- Personal/fun: $200/month
15th paycheck ($2,100) — covers the 16th through the 31st:
- Rent half #1 (half-payment method): $800
- Savings half #1: $200
- Phone: $75
- Internet: $70
- Credit card minimum: $90
- Groceries (half): $250
- Gas (half): $110
- Personal (half): $100
- Subscriptions: $45
- Total: $1,740 → $360 left as buffer
30th paycheck ($2,100) — covers the 1st through the 15th:
- Rent half #2: $800 (rent now fully funded before the 1st)
- Savings half #2: $200
- Car payment: $385
- Car insurance: $175
- Electric: $140
- Groceries (half): $250
- Gas (half): $110
- Personal (half): $100
- Total: $2,160 → this is $60 over!
Notice what the example revealed: the second paycheck came out $60 over before we touched anything. That's not a failure — that's the system doing its job. You found the shortfall on paper, where it's free, instead of on the 9th, where it costs overdraft fees. The fix is honest and small: shift $60 of grocery spending into the first half (the 15th paycheck has a $360 buffer), or trim one subscription. The Federal Reserve reports that nearly 4 in 10 Americans would struggle to cover a $400 emergency — catching a $60 gap before it happens is exactly how you stop being one of them.
Once adjusted, the month looks like this: all bills paid, $400 saved, $200 of personal spending intact, and a small buffer left over. That's a paycheck budget doing what a monthly budget couldn't — telling you the truth twice instead of never.
How to Budget Twice a Month Without Doing Double the Work
The most common objection to learning how to budget twice a month is: "So I have to do budgeting work twice as often?" Fair question. The answer is that the first month is the heavy one, and every month after is nearly automatic.
- Month one: Build both paycheck plans on paper or in our budget planner. This takes about an hour.
- Month two: Copy them over. Only update what changed (a new bill, a raise, a cancelled subscription). This takes ten minutes.
- Month three onward: It runs on autopilot — automatic transfers on the 15th and 30th, bills already mapped, savings already scheduled.
Three automations carry the whole load: (1) split your direct deposit or set two recurring transfers — rent half and savings half leave your account every payday; (2) set bill autopay for the day after each paycheck's bills are funded, never the day before; (3) keep a "payday checklist" on your phone notes — five lines you glance at on the 15th and 30th. That's the entire maintenance burden.
Three Traps That Break Semi-Monthly Budgets (and How to Fix Them)
Trap 1: Treating the 30th paycheck as "next month's money." It's not. It funds the 1st through the 15th. If you spend it freely, rent week becomes a crisis. Fix: name it mentally — "this is my 1st-of-the-month paycheck."
Trap 2: Forgetting the variable costs have halves too. People carefully split the bills, then spend groceries and gas "from whichever paycheck feels right." It always feels like the 15th one. Fix: give yourself a weekly spending number instead — for $500 groceries, that's $125 a week, no matter which half of the month it is. Our guide on the 50/30/20 budget rule pairs well here as a gut-check on whether your spending splits are sane.
Trap 3: The five-week month. Every few months, the gap between the 30th and the next 15th stretches to 16 or 17 days. Budgeted-for-two-weeks spending meets two-and-a-half-weeks of reality. Fix: that paycheck buffer from the 15th half exists precisely for this. If you consistently feel the squeeze, run a quick subscription audit and redirect the recovered money into your buffer.
Make the Math Automatic
Here's your move today: open our free budget planner and plug in your two paychecks and your bills by due date. Run the halves. If a paycheck comes up over, you just found the gap before it cost you anything — adjust a variable cost or a due date, and you're balanced.
Then do the one thing that makes it stick: on the next 15th, move the first rent half and the first savings half the moment the paycheck lands. Not tomorrow. Not "when I get around to it." The whole secret of semi-monthly budgeting is that each paycheck funds its own half before the spending starts. Do that twice, and the system is running.
Getting paid twice a month used to feel like a budgeting disadvantage — all timing, no rhythm. Done this way, it's the opposite: you get two clean restarts every month, two chances to fund savings, and a system that catches problems on paper instead of in your bank app. Two paychecks, two plans, zero mystery. That $360 buffer from the first half isn't luck. It's what a budget that matches your paydays looks like.
We're a small team of personal-finance writers who test every strategy on our own budgets first. Our guides are researched from primary sources like the CFPB, the Federal Reserve and the IRS — and updated when the numbers change. No hype, no get-rich-quick promises: just practical money help that works on a real paycheck.
Frequently Asked Questions
What is a semi-monthly budget?
A semi-monthly budget is a plan for people paid twice a month — usually on the 15th and 30th. Instead of one monthly budget, you give each paycheck its own bill list based on due dates: bills due 16th–31st come from the 15th paycheck, and bills due 1st–15th come from the 30th paycheck.
How do I split bills between two paychecks?
List every bill with its due date. Assign bills due between the 16th and 31st to your 15th paycheck, and bills due between the 1st and 15th to your 30th paycheck. Split variable costs like groceries and gas roughly in half, and use the half-payment method for big bills like rent so no single paycheck takes the full hit.
Is the half payment method worth it?
Yes — especially when a bill like rent is bigger than half of one paycheck. Splitting $1,600 rent into two $800 halves means the full amount is ready before the 1st and neither paycheck feels strained. It works for car payments, insurance premiums, and savings goals too.
How much should I save from each paycheck?
Move a fixed amount to savings on payday morning before anything else — even $100–$200 per paycheck builds $2,400–$4,800 a year. Aim for 10–20% of each paycheck once the habit is established, and see our emergency fund guide for where to keep it.
What if my bills don't line up with my paychecks?
Ask providers to change your due dates — most credit card companies, utilities, and lenders will do it at no cost. Move bills to land a few days after each payday, and bunch the flexible ones into whichever half has more breathing room.
Can I budget by paycheck instead of monthly?
Absolutely — and for semi-monthly pay it's usually better. Budget by paycheck means planning what each paycheck must cover before the next one lands, which matches the rhythm your money actually arrives in. That timing match is exactly why it works where a single monthly budget fails.